A renewal questionnaire just asked about knob and tube, or an underwriter’s letter gave you a deadline, and you don’t know what to send back. A vague answer stalls the process. A specific one moves it.
At Northloom Minneapolis Knob and Tube, we write knob and tube insurance letters and wiring records in Minneapolis and St. Paul, based on circuits we trace and test. Our letter answers the question insurers actually ask, whether any knob and tube is still energized, in writing your agent can act on.
Insurance is one of the most common reasons people call us. It might be a new policy application, a renewal questionnaire or a letter with a date in it. In each case, the answer starts with knowing which of your circuits carry power.
What happens when you come out?
We do a full circuit evaluation, with your insurer’s request in hand.
- The request
- We read your insurer’s letter or questionnaire first, so the record answers what was asked.
- Tracing
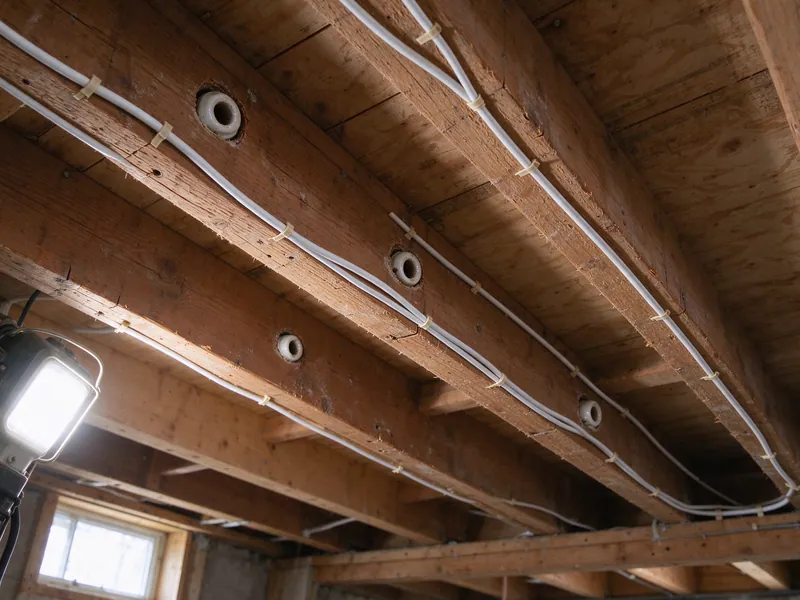
- We match every circuit to its rooms and identify it as original, cloth-covered or modern.
- Testing
- We test the original circuits to see which carry power.
- Conditions
- We note insulation contact, fuse sizes and ungrounded outlets, since underwriters often ask.
- Next step
- If work is needed, a scope matched to your insurer’s requirement.
What does my insurer actually want to see?
Carriers phrase it differently, but most want a few specific things.
| What they ask | What answers it |
|---|---|
| Is any knob and tube still in use? | A circuit list showing live and dead original circuits |
| Has the wiring been updated, and when? | A record of replaced circuits with permit and inspection |
| Is the old wiring disconnected? | Where each original circuit was disconnected and how it was tested |
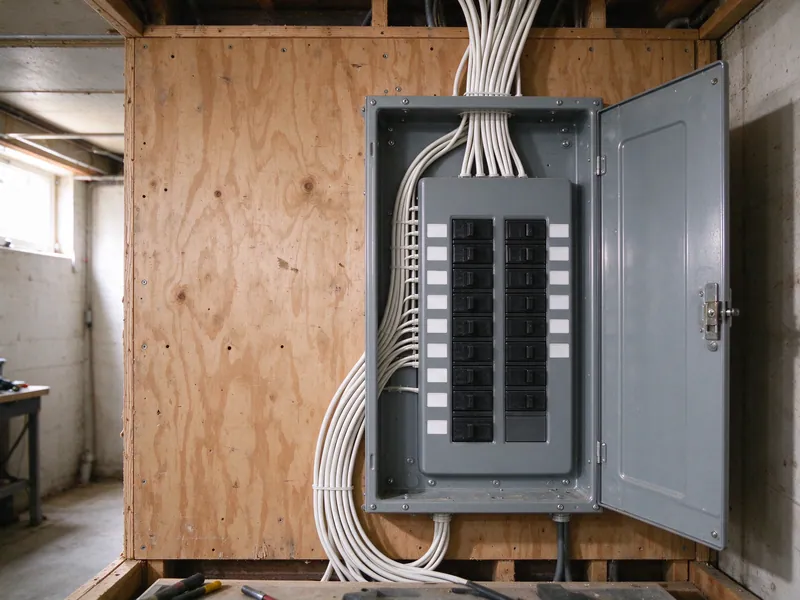
| What size is the electrical service? | The panel and service size, with breakers or fuses noted |
| Who did the work? | The permit record for the work |
Ask your agent for the exact wording the underwriter needs before we visit, and we’ll write the record to answer it directly.
How much time do I have before they can drop me?
For a policy already in force, Minnesota’s rules set a process an insurer must follow before nonrenewing over a known condition it wants corrected.
- First written request
- States the condition and why it raises the risk of loss, and gives the time limits for fixing it.
- Second written request
- Repeats the request and states the intent to nonrenew if it isn’t corrected.
- What that means for you
- There’s usually time to trace, decide the scope and do the work, as long as you start when the first letter arrives.
New policy applications are different: a carrier can decline to write a policy at the outset. Minnesota’s FAIR plan insures property the regular market declines; it may inspect, and it can accept a property only once the improvements it notes are made and confirmed. The guide to insurer deadlines covers the timeline in detail.
What can your letter promise, and what can’t it?
A letter is only as strong as what stands behind it, so ours sticks to what we traced and tested.
| Our letter can state | Our letter can’t state |
|---|---|
| Which circuits we traced and tested, and the result | That concealed wiring nobody could see is in good condition |
| Where original circuits were disconnected and how we confirmed it | That nothing in the house will ever fail |
| What new work was done, under which permit | What the insurer will decide |
| Conditions we observed during the evaluation | Anything beyond the date it was written |
A careful letter states its limits, and that protects you too. An underwriter who later finds a live run a letter said didn’t exist will trust the next letter less.
What record do I get if the insurer wants work done?
When your insurer requires work, the record after replacement is stronger than any evaluation letter, because a permit and inspection stand behind it.
- Circuit list
- Every circuit, now marked modern, with the rooms it feeds.
- Disconnections
- Each original circuit, where it was disconnected and how we tested it dead.
- Permit
- The permit and the rough-in and final inspection dates.
- Panel directory
- A typed directory matching the list.
Keep it with your policy papers and house records. A future buyer’s insurer will ask the same question.
I rent out my building or own a condo. Does this apply to me?
Yes. Insurance questions about wiring don’t stop with homeowners.
- Landlords
- Rental and landlord policies often ask the same question homeowner policies do, unit by unit. A record for each unit of a duplex or triplex answers it.
- Residents
- Insurance held by the people living there rarely asks about building wiring, but a resident who sees knob and tube may ask you what’s been done. The building record is your answer.
- Condo owners
- In a converted older building, the association’s master policy and each owner’s policy may ask about different parts of the wiring. The record states which circuits serve which unit and which serve common areas.
When should I schedule the evaluation?
Close to when you’ll send the letter. A wiring record describes your house on the day we traced it, and an insurer gives a recent record more weight than an old one. If a remodel or repair changes circuits after the letter, ask for an updated record. Keep every version with your house papers, dated, so a later agent or buyer can see how the wiring changed over time.
What does a wiring letter cost?
The letter comes from the evaluation, and our typical range for a knob and tube evaluation is $150 to $500. Where yours falls depends on the size of your house, how many circuits there are and how much of the attic and basement we can reach. If your insurer then requires work, the scope and price for it follow from the same traced circuit list.
Which work matches what my insurer is asking for?
The right work depends on what your carrier requires, and the record makes that choice clear.
| Insurer’s requirement | Usual scope |
|---|---|
| No knob and tube energized | Partial replacement of live original circuits, plus disconnection of the rest |
| No knob and tube in use or in the house | Partial or whole-house replacement, plus removal of exposed runs |
| A full update of older wiring | Whole-house rewiring, often with a panel upgrade |
| Documentation only | The evaluation letter |
The homeowners insurance guide explains how carriers commonly treat each, and the cost guide shows how scope drives the price.
We write the record to be forwarded as it is. It names the property, the date of the evaluation, what we traced and tested, and the conclusion, in plain language an underwriter can read without a follow-up call.